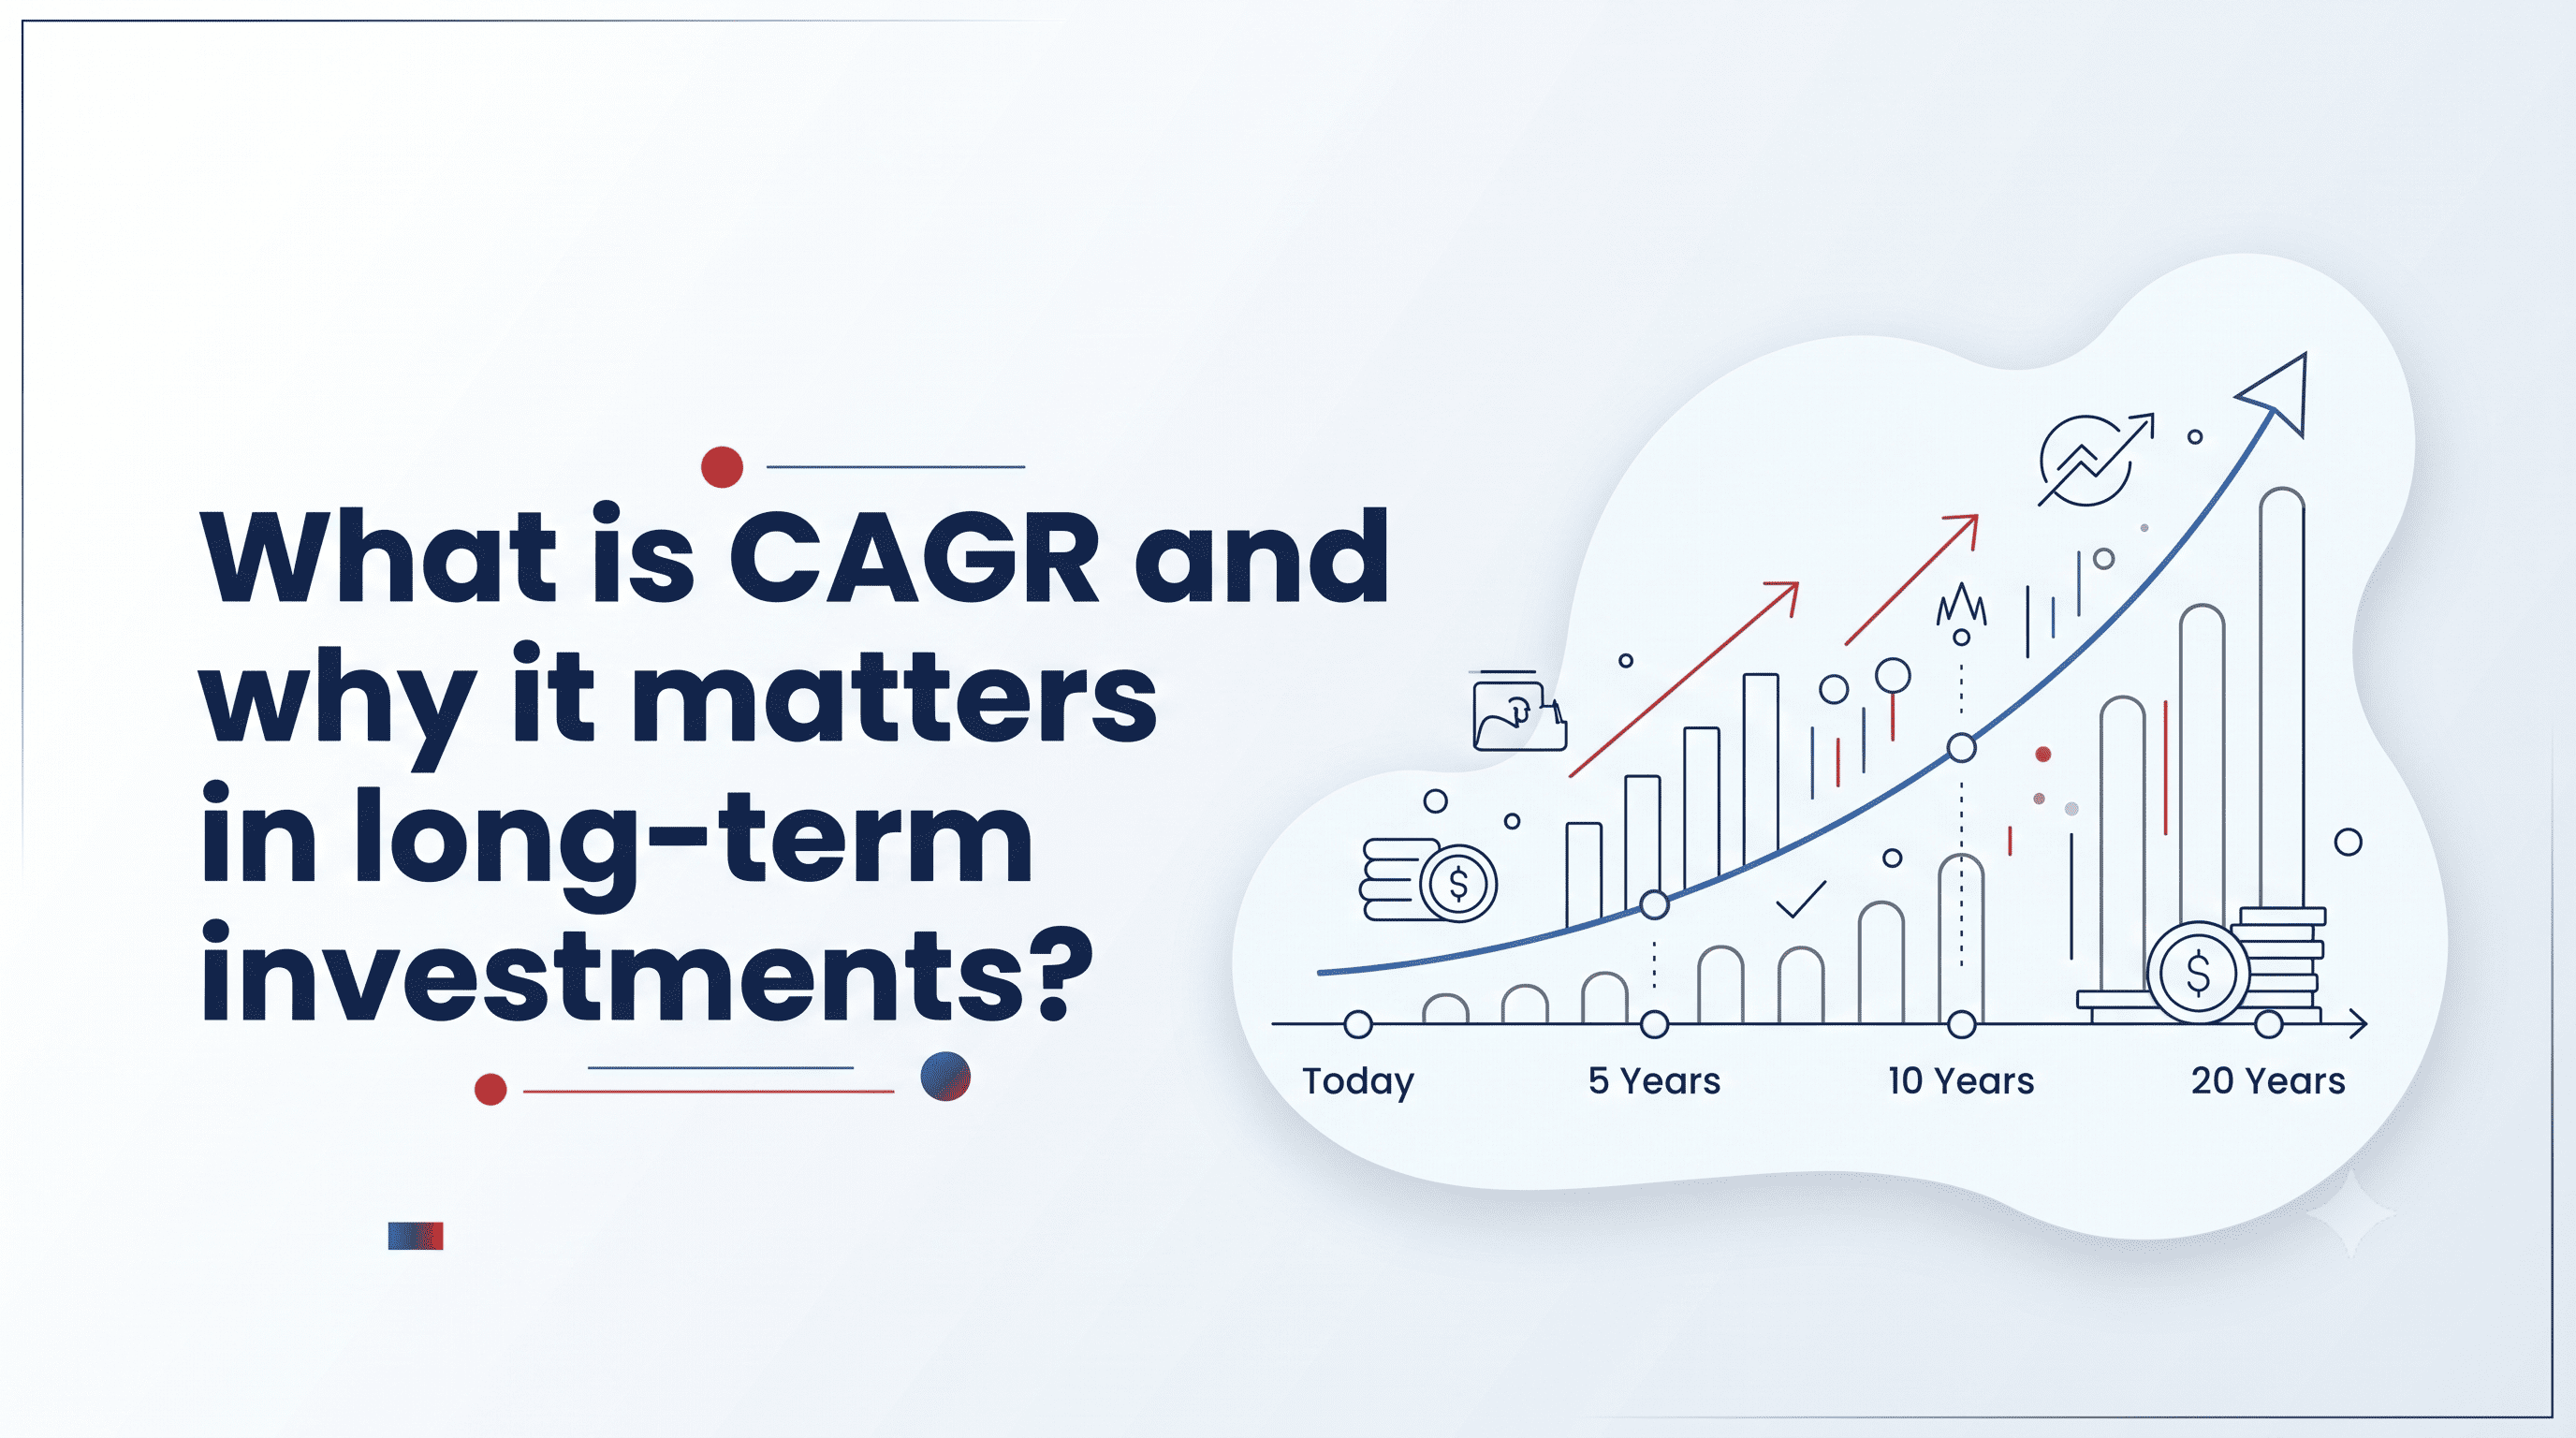
Compounded growth in an insurance-linked plan refers to the potential appreciation of your total fund value as market-linked returns are reinvested over time. The growth of your corpus is driven by the performance of the underlying ETFs and is reflected in the daily Net Asset Value (NAV) of your chosen funds. In investment-linked products, growth results from reinvested returns rather than fixed interest.
Difference between simple and compound interest
Unlike fixed-interest products, a ULIP allows your net investible premium to grow through market participation, where any appreciation stays invested to participate in future market movements.
Why compounding is critical for long-term wealth creation
Compounding is vital for long-term wealth creation. This is because your earnings and deposits can generate returns, leading to considerable growth over time. It is a snowball effect, meaning that the longer you invest, the faster it has the potential to grow into a substantial financial corpus over a long-term horizon.
Benefits of Compound Interest for NRI Investors
Here are some of the advantages of compound interest investments for NRIs.
Accelerated growth of USD-denominated investments
You can choose from a range of USD-denominated ETFs that offer the potential for long-term capital appreciation based on global market performance. This helps you accelerate your portfolio’s growth due to the interest-on-interest effect.
Mitigating currency fluctuation risks with global investments
You can combat the risks related to currency fluctuations with global investments. The US dollar is widely used in global trade and finance. For internationally mobile investors, USD-denominated investments may offer an additional avenue for currency diversification.
Building a financial corpus for education, retirement, and wealth creation
You can easily use compound interest investments to accumulate funds for future wealth creation and estate planning, retirement, and even paying for the higher education of your children.
HDFC Life International’s Investment-Linked Insurance Solutions
HDFC Life International offers strategic USD-based and investment-linked insurance solutions to help you meet your future financial goals. These plans provide a dual benefit: life insurance protection for your family and market-linked growth through diversified ETF strategies.
Flexibility to invest according to financial goals and risk appetite
You can flexibly invest with personalisation based on your risk tolerance/appetite, financial goals, and ability to stay invested to meet various objectives.
Regulated safety through IFSCA and operations in GIFT City
HDFC Life International operates as an IFSC Insurance Office regulated by the International Financial Services Centres Authority (IFSCA). At the same time, operations across GIFT City in India ensure transparent governance and cross-border accessibility, helping you harness global investment opportunities.
Strategies to Maximise Returns from Compound Interest Investments
Here are some ways in which you can maximise your returns from compound interest investments.
Start early and invest regularly to leverage compounding
Start as early as possible and invest regularly to leverage the benefits of compounding. Long-term and consistent investing allows your returns to build upon themselves, helping you create a sizable corpus over time.
Choosing long-term plans with reinvestment options
Compounding only works strategically when you invest for the long haul. Thus, it’s important to choose long-term plans that have reinvestment options. This will help you stay invested and reap the massive benefits of compounding after a certain point in time.
Monitoring and rebalancing your portfolio periodically
You should always review your portfolio periodically, making sure that your investments are on track towards achieving their financial outcomes. This will help you track, rebalance, and review for the best possible outcomes.
Remember, the effect of compounding depends on reinvested gains and time in the market, not on a fixed interest rate.
How to Choose the Right Compound Interest Investment Plan
Wondering how to select the right compound interest investments? Here is a guide that will help.
Assessing risk tolerance and investment horizon
You should carefully evaluate your appetite for risk and your desired horizon for investments at the outset. This will serve as a guide towards helping you choose the right investment plan.
Comparing performance, fees, and liquidity options
When evaluating investment-linked insurance plans, review factors such as historical fund performance, applicable fees and charges, and the plan’s liquidity features. Charges may affect the overall value of your investment over time. It is also important to understand withdrawal conditions and any lock-in periods before investing.
Understanding tax implications for NRIs on USD-based investments
Knowing the taxability and tax outgo for your USD-based investments is also vital when you’re an NRI. Tax treatment varies by your country of residence, India’s IFSC framework, and any applicable Double Taxation Avoidance Agreement (DTAA).